
Longer Days, Warmer Weather: Embrace the Spring Glow-Up—Financing Your Outdoor Home Upgrades This Season
As the winter chill finally recedes from the Blue Ridge Mountains and the days begin to stretch longer, homeowners in Johnson City, TN, and the surrounding Tri-Cities area are feeling that familiar itch. It is the urge to step outside, breathe in the fresh spring air, and finally tackle those home improvement projects that have been hibernating all winter. We call it the “Spring Glow-Up”—that transformative time when your home sheds its winter coat and gets ready for backyard barbecues, porch sitting, and outdoor entertaining.
However, visualizing a stunning new deck, a stamped concrete patio, or a lush landscape design is the easy part. The challenge often lies in the logistics: How do you pay for it without draining your savings account?
At the Arrowood Team at Preferred Rate, we believe that your dream home shouldn’t be limited by your checking account balance. Whether you are looking to boost your property value or simply create a personal oasis in East Tennessee, understanding your financing options is the first step toward breaking ground. In this comprehensive guide, we will explore how to leverage your home’s equity to fund your outdoor upgrades this season.
Why Spring is the Perfect Time for Outdoor Upgrades in East Tennessee
There is a strategic reason why spring is the peak season for renovations in Johnson City. Beyond the obvious benefit of warmer weather facilitating construction, timing your “glow-up” now has distinct advantages for local homeowners.
- Maximize Enjoyment: By securing financing and starting construction in early spring, your projects are typically completed by summer. This ensures you get to enjoy your new pool, patio, or outdoor kitchen during the prime warm months.
- Boost Curb Appeal for Selling Season: If you are considering listing your home, the spring real estate market in the Tri-Cities is historically robust. Fresh landscaping and functional outdoor living spaces are top selling points for buyers in our region.
- Contractor Availability: While demand is high, getting on a contractor’s schedule early in the season prevents the long wait times that occur by mid-summer.
Top Outdoor Projects That Boost ROI in Johnson City
Before we dive into the “how” of financing, let’s look at the “what.” Not all renovations are created equal. When planning your spring glow-up, consider projects that offer a high Return on Investment (ROI), specifically for the Tennessee housing market.
1. The Outdoor Living Room
In Johnson City, where our autumns are long and our springs are mild, an outdoor living room extends your square footage. Think covered pergolas, fire pits, and comfortable seating areas. This blurs the line between indoor and outdoor living, a highly desirable feature for local buyers.
2. Deck Additions and Refinishing
Given the hilly terrain of East Tennessee, many homes feature walk-out basements or elevated main floors. A sturdy, composite deck not only provides a vantage point for mountain views but also recovers a significant portion of its cost upon resale.
3. Curb Appeal Landscaping
First impressions matter. Professional landscaping—including sod installation, native planting, and hardscaping—can increase perceived home value by 5-12%. It sets the tone for the entire property.
Financing Your Glow-Up: Exploring Your Options
Unless you have a substantial amount of cash sitting idle, financing is the engine that will drive your renovation. As a mortgage expert serving Johnson City, Tim Arrowood helps homeowners navigate the complex world of lending to find the tool that best fits their financial profile. Here are the primary ways to finance your outdoor renovation.
1. Cash-Out Refinance
A cash-out refinance replaces your current mortgage with a new one that is larger than your remaining loan balance. You receive the difference in tax-free cash, which you can use for your renovations.
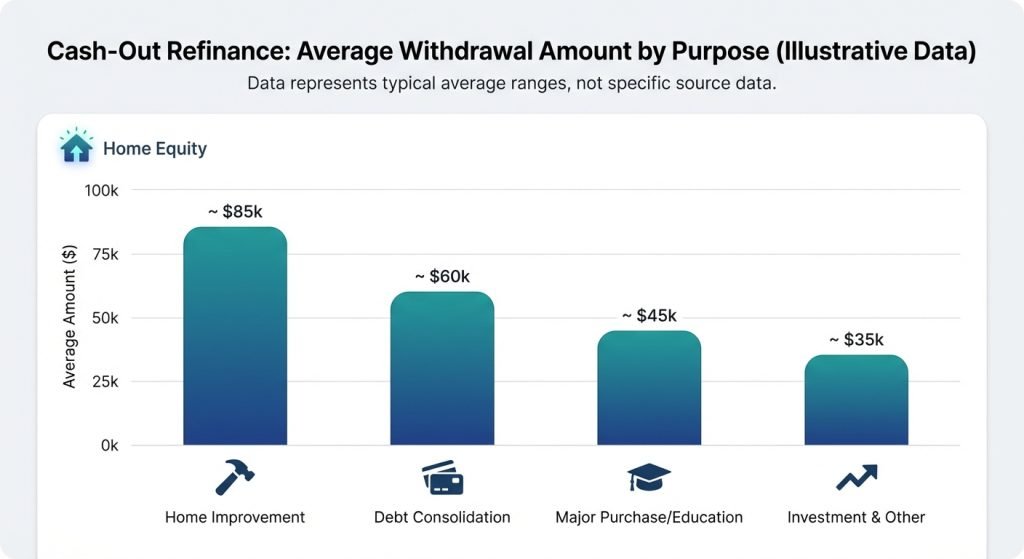
When to choose this: This is an excellent strategy if you have built up significant equity in your home and plan to stay in the property for several years. It allows you to consolidate your renovation costs into one monthly payment, often at a lower interest rate than credit cards or personal loans.
2. Home Equity Line of Credit (HELOC)
A HELOC works like a credit card secured by your home. You are given a credit limit based on your equity, and you can draw from it as needed. You only pay interest on the amount you actually use.
When to choose this: If you are planning a project with phased costs (like a landscaping overhaul that takes months) or if you are unsure of the final price tag, a HELOC offers flexibility. It is also a great option if you currently have a very low interest rate on your primary mortgage that you do not want to touch.
3. Home Renovation Loans (FHA 203k or Fannie Mae HomeStyle)
These are specialized loans that allow you to borrow based on the future value of the home after renovations are complete, rather than its current value.
When to choose this: These are ideal for “fixer-uppers” or if you have limited equity but big plans. If you are buying a home in Johnson City that needs a new deck or major exterior work, you can roll the renovation costs directly into your purchase mortgage.
Comparing Your Financing Options
To help you visualize which path might be right for your spring project, review the comparison table below. Remember, every financial situation is unique, so consulting with the Arrowood Team is recommended for a personalized analysis.
| Feature | Cash-Out Refinance | HELOC | Personal Loan |
|---|---|---|---|
| Interest Rate Type | Typically Fixed | Typically Variable | Fixed |
| Closing Costs | Yes (Standard Mortgage Costs) | Lower or None | None |
| Tax Deductible? | Potentially (If used for capital improvements) | Potentially (If used for capital improvements) | No |
| Best For | Large, one-time projects; Debt consolidation | Ongoing projects; Flexibility | Small projects; Quick funding needs |
| Loan Term | 15 to 30 Years | 10-Year Draw Period (typ.) | 3 to 7 Years |
The Arrowood Team Advantage: Local Expertise Matters
When you are looking for mortgage solutions in Johnson City, you have endless options online. However, real estate and lending are hyper-local industries. Here is why working with Tim Arrowood and the Arrowood Team at Preferred Rate makes a difference:
- We Know the Market: We understand the specific value that outdoor upgrades bring to homes in the Tri-Cities. We can help guide you on how much equity you can safely leverage without over-improving for the neighborhood.
- Personalized Strategy: We don’t use a “one-size-fits-all” algorithm. We look at your overall financial picture—your retirement goals, your current cash flow, and your long-term plans for the home—to structure a loan that supports your life, not just your renovation.
- Speed and Communication: Spring is a busy season. You need a lender who answers the phone, communicates with your contractors if necessary, and closes on time so your project isn’t delayed.
Whether you are looking to explore loan options or simply want a second opinion on a quote you received elsewhere, we are here to serve our neighbors.
Expert Tips for Planning Your Project
Before you sign on the dotted line for a loan, ensure your project is set up for success.
- Get Multiple Quotes: Labor and material costs in Tennessee have fluctuated recently. Get at least three quotes from licensed local contractors to ensure you are getting a fair price.
- Buffer Your Budget: Renovation projects almost always uncover hidden costs. When calculating how much equity to pull out, add a 10-15% contingency fund to your total.
- Check HOA Regulations: Many neighborhoods in Johnson City have Homeowners Associations with strict rules regarding exterior modifications. Ensure your financing and plans align with their bylaws.
Frequently Asked Questions (FAQs)
1. How much equity do I need to qualify for a cash-out refinance?
generally, lenders require you to maintain at least 20% equity in your home after the cash-out transaction. This means you can typically borrow up to 80% of your home’s current appraised value. However, programs vary, so it is best to contact Tim Arrowood for a specific calculation based on your property.
2. Is the interest on a home improvement loan tax-deductible?
Under current tax laws, the interest paid on a mortgage or HELOC may be tax-deductible if the funds are used to “buy, build, or substantially improve” the home that secures the loan. We recommend consulting with a tax professional to see if your specific project qualifies.
3. How long does the refinancing process take?
On average, a refinance can take anywhere from 30 to 45 days. The timeline depends on how quickly we can order the appraisal and receive the necessary documentation. The Arrowood Team prides itself on efficiency and will work to close your loan as quickly as possible.
4. Can I do the work myself (DIY) with a renovation loan?
If you are using a standard Cash-Out Refinance or a HELOC, the bank generally does not monitor who performs the work. You are free to DIY. However, specialized renovation loans like the FHA 203k usually require the use of licensed, professional contractors to ensure the work meets code and value standards.
5. What if I have a low credit score? Can I still finance a renovation?
Credit score requirements vary by loan type. While conventional loans typically require higher scores, FHA loans (including the 203k renovation loan) often have more flexible credit guidelines. Don’t assume you are disqualified—reach out to us for a consultation.
Ready to Start Your Spring Glow-Up?
The birds are chirping, the flowers are blooming, and your dream outdoor space is waiting to be built. Don’t let financing hurdles keep you indoors this season. Whether you need a cash-out refinance to build that sprawling deck or a renovation loan to install a pool, Tim Arrowood and the team are ready to help you secure the funds you need.
Contact us today to discuss your project and discover how much equity you can unlock!
Tim Arrowood | The Arrowood Team
Preferred Rate – Partnered with APM
Phone: 423-406-1567
Email: tim.arrowood@preferredrate.com
Related guides from The Arrowood Team
- DSCR Loans for 1–4 Unit Investment Properties: A Real-World Guide
- The Ultimate Guide to Securing a Foreign National Mortgage in Johnson City, TN
- Navigating Mortgage Options in 2026: AI Tools and Non-QM Loans
Ready to move forward? Start your application or see how the $5,000 Closing Guarantee strengthens your offer.
