
Longer Days, Warmer Weather: Spring Home Hunting Made Easier—Get Pre-Approved Now to Beat the Seasonal Surge
As the winter chill begins to fade from the Blue Ridge Mountains and the days start stretching longer, a familiar energy returns to Johnson City, Tennessee. The flowers are blooming, the “For Sale” signs are popping up on manicured lawns, and the local real estate market is waking up from its winter slumber. Spring is widely recognized as the peak season for real estate, and for good reason. The warmer weather makes house hunting more enjoyable, families are eager to move before the next school year, and inventory levels typically hit their highest point of the year.
However, with increased inventory comes increased competition. The “Spring Surge” is real, and in a desirable market like the Tri-Cities, waiting until you find the perfect home to sort out your financing is a risky strategy. To truly capitalize on the longer days and warmer weather, you need to be prepared before you even step foot in an open house. This comprehensive guide will explain why getting pre-approved now is your secret weapon for spring home hunting success in Johnson City.
Why Spring is the Prime Time for Real Estate in Johnson City
There is a psychology to the spring housing market that drives activity. After months of being cooped up indoors, buyers are eager for a fresh start. In Johnson City and the surrounding Washington County areas, the spring market brings a specific set of dynamics that every prospective buyer should understand.
1. Inventory Spikes
Many sellers wait specifically for spring to list their homes. They know that curb appeal is at its peak when the grass is green and the dogwoods are in bloom. For buyers, this means more options. Whether you are looking for a historic home near ETSU, a modern build in North Johnson City, or a quiet retreat near Boone Lake, you will likely see more listings hitting the Multiple Listing Service (MLS) in April and May than in previous months.
2. The “School Year” Clock
Families are a major driving force in the spring market. Parents often want to close on a home and settle in during the summer months to ensure a smooth transition for their children before the new school year begins. This creates a natural deadline that accelerates the pace of the market.
3. Better Weather for Inspections and Viewing
Let’s face it: viewing homes in the freezing rain isn’t fun. Spring weather allows for more thorough inspections of exteriors, roofs, and landscaping. It also makes the process of driving from neighborhood to neighborhood much more pleasant, encouraging buyers to see more properties in a single day.
The Challenge: Dealing with the “Spring Surge” Competition
While more inventory is great news, it attracts more buyers. The Tri-Cities area has seen significant growth recently, and competition for well-priced homes can be fierce. In a seller’s market, or even a balanced one, a “hot” property might receive multiple offers within the first 48 hours of listing.
If you find your dream home on a Saturday afternoon but haven’t spoken to a lender, you are already behind. By the time you reach out to a bank on Monday morning, another buyer who was already pre-approved may have already submitted a binding offer. This is where The Arrowood Team steps in to give you the competitive edge.
The Ultimate Spring Homebuying Hack: Mortgage Pre-Approval
Many first-time homebuyers confuse “pre-qualification” with “pre-approval,” but in the eyes of a seller, they are worlds apart. A pre-approval is not just a casual estimate; it is a verified indication of your purchasing power.
What is a Mortgage Pre-Approval?
A mortgage pre-approval is a formal document from a lender stating that they are willing to lend you a specific amount of money based on a thorough review of your financial health. To issue this, Tim Arrowood and his team will verify your income, employment status, assets, and credit history. It is essentially a “green light” that tells real estate agents and sellers that you are a serious, qualified buyer.
The Difference Between Pre-Qualification and Pre-Approval
Understanding this distinction is vital for your strategy. See the comparison below:
| Feature | Pre-Qualification | Pre-Approval |
|---|---|---|
| Definition | An estimate of what you might be able to borrow based on self-reported data. | A conditional commitment to lend based on verified documentation. |
| Verification | None. Credit is usually not pulled (or only a soft pull). | Rigorous. Credit report, W-2s, pay stubs, and bank statements are reviewed. |
| Seller Perception | Seen as a casual interest; holds little weight in negotiations. | Seen as “good as cash”; highly attractive to sellers. |
| Speed to Close | Slower; the underwriting process hasn’t started yet. | Faster; much of the heavy lifting is already done. |
Strategic Advantages of Pre-Approval in the Local Market
When you are house hunting in Johnson City this spring, walking around with a pre-approval letter in your pocket changes the entire dynamic of the process.
1. You Know Your True Budget
There is nothing worse than falling in love with a home only to realize later that the monthly payments are outside your comfort zone. Pre-approval gives you a concrete price ceiling. It factors in current interest rates, property taxes in Washington County (or surrounding areas), and insurance estimates, allowing you to hunt with confidence.
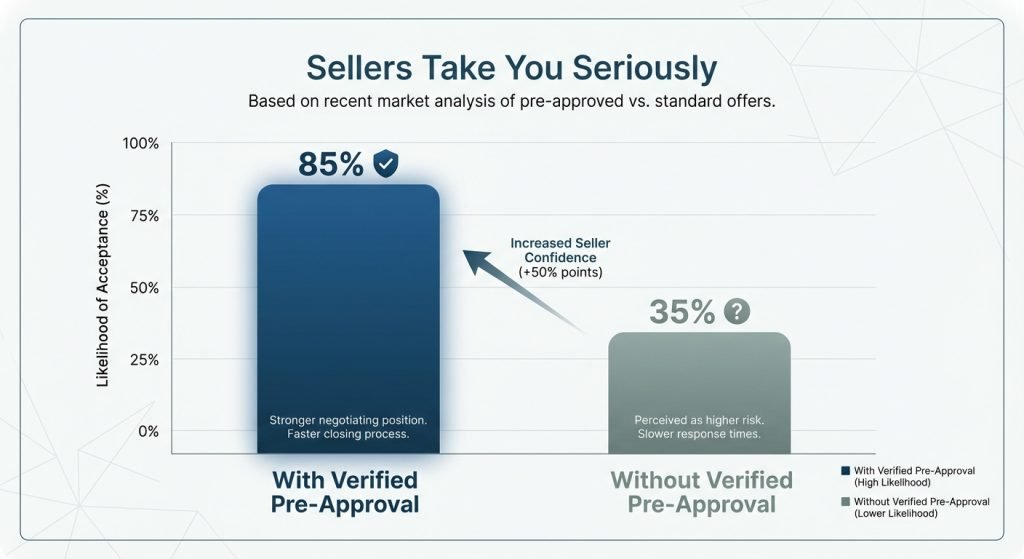
2. Sellers Take You Seriously
Imagine a seller receives two offers on their home. Offer A is higher but comes with a generic pre-qualification letter. Offer B is slightly lower but comes with a solid pre-approval from a reputable local lender like Preferred Rate. The seller is often more likely to accept Offer B because there is significantly less risk of the financing falling through at the last minute.
3. Faster Closing Times
Since your financial background has already been vetted, the time from “offer accepted” to “closing table” is often shorter. In a competitive spring market, promising a quick close can be a major bargaining chip.
4. Negotiating Power
The Arrowood Team: Your Local Mortgage Partners
Navigating the mortgage landscape can be complex, but you don’t have to do it alone. Tim Arrowood and The Arrowood Team at Preferred Rate are deeply embedded in the Johnson City community. We understand the nuances of the local market better than big-box national lenders or impersonal online algorithms.
Why choose The Arrowood Team for your Spring Pre-Approval?
- Local Expertise: We know the Tri-Cities market, local appraisers, and real estate agents. This local network facilitates smoother transactions.
- Personalized Service: You aren’t just a loan number to us. We take the time to understand your financial goals and match you with the right loan product, whether that’s Conventional, FHA, VA, or USDA.
- Speed and Efficiency: We know that in the spring market, speed wins. We work diligently to get your pre-approval ready so you can make offers without delay.
Your Spring Homebuying Checklist
- Proof of Income: Gather your last 30 days of pay stubs and W-2 forms for the past two years.
- Tax Returns: Have your federal tax returns for the last two years ready, especially if you are self-employed.
- Asset Documentation: Collect bank statements (checking and savings) and investment account statements for the last two months.
- Identification: A valid driver’s license or passport.
- Debt Information: A general idea of your monthly debts (student loans, car payments, credit cards) helps, though we will pull a credit report to verify this.
Don’t Let the Spring Market Pass You By
The days are getting longer, and the weather is getting warmer. This is the perfect time to find your dream home in Johnson City. But remember, the most successful home hunters are the prepared ones. By securing your pre-approval now, you can beat the seasonal surge, shop with confidence, and move quickly when the right property appears.
Don’t wait until you find the house to think about the loan. Get the hard work out of the way now so you can enjoy the fun part of home shopping!
Frequently Asked Questions (FAQs)
1. How long does a mortgage pre-approval last?
Generally, a pre-approval letter is valid for 60 to 90 days. This is because your financial situation (income, credit score, debts) and interest rates can change over time. If your house hunt takes longer than three months, The Arrowood Team can easily update your pre-approval with fresh documentation.
2. Does getting pre-approved hurt my credit score?
Getting pre-approved requires a “hard inquiry” on your credit report, which typically lowers your score by a few points (usually less than 5). However, this is a necessary step to get a mortgage. If you shop around with multiple lenders within a short window (typically 14-45 days), credit bureaus usually treat these as a single inquiry, minimizing the impact.
3. I’m a first-time homebuyer in Johnson City. Are there special programs for me?
Absolutely! There are various loan programs designed to help first-time buyers, including FHA loans which require lower down payments, and USDA loans which offer 0% down payment options for eligible rural and suburban areas around Johnson City. During your pre-approval process, we will identify which programs you qualify for to maximize your savings.
4. Can I make an offer on a house without a pre-approval letter?
Technically, yes, you can make an offer. However, in a competitive spring market, most sellers and real estate agents will not take your offer seriously without proof of funds or a pre-approval letter. Many listing agents advise their clients not to accept offers from buyers who haven’t secured financing, as the risk of the deal falling through is too high.
5. What if I have some debt? Can I still get pre-approved?
Yes, you can! Lenders look at your Debt-to-Income (DTI) ratio, not just the existence of debt. Many loan programs allow for DTI ratios of up to 43% or even higher in some cases. Don’t disqualify yourself before you talk to a professional. Tim Arrowood can review your specific situation and help you understand your borrowing power.
Ready to Start Your Home Search?
Take the first step toward your new home today. Contact Tim Arrowood and The Arrowood Team at Preferred Rate to get your pre-approval started. Let us help you turn your spring homeownership dreams into reality.
Contact Tim Arrowood:
- Phone: 1-423-406-1567
- Email: tim.arrowood@preferredrate.com
Disclaimer: The information provided in this blog post is for educational purposes only and does not constitute financial or legal advice. Mortgage rates and program guidelines are subject to change without notice. Please consult with a qualified mortgage professional for advice specific to your situation.
Related guides from The Arrowood Team
- First-Time Home Buyer Loans in Johnson City, TN
- Your Guide to a First-Time Homebuyer Mortgage in Johnson City
- First-Time Homebuyer’s Roadmap for 2026: Overcoming Affordability in Johnson City, TN
- THDA and Tri-Cities First-Time Buyers 2026: Down Payment Help for Johnson City, Kingsport, and Bristol
Ready to move forward? Start your application or see how the $5,000 Closing Guarantee strengthens your offer.
