
VA Loans in the Tri-Cities and Southwest Virginia 2026: Advanced Moves Most Lenders Still Miss
Insider Strategies for Maximizing Your VA Loan Benefits
As we move into 2026, the real estate market in the Tri-Cities and Southwest Virginia continues to offer incredible opportunities for veterans and active-duty military personnel. However, many local homebuyers are leaving money on the table because they are not fully utilizing their benefits. At The Arrowood Team, we specialize in advanced VA loan strategies that most traditional lenders overlook.
- Flexible Credit Requirements: While some banks demand pristine credit, we understand that life happens. We offer VA loan options with credit scores down to 580.
- Entitlement Optimization: Learn how to use your remaining entitlement to purchase a second home or upgrade your current residence without selling.
- Local Incentives: Discover how to pair your VA benefits with Tennessee and Virginia state-specific grants.
If you are looking to buy a home in Johnson City, Kingsport, Bristol, or the surrounding areas, working with a specialized local mortgage broker like Tim Arrowood can make all the difference in securing the best possible terms.
Mastering IRRRL Timing and Entitlement Optimization
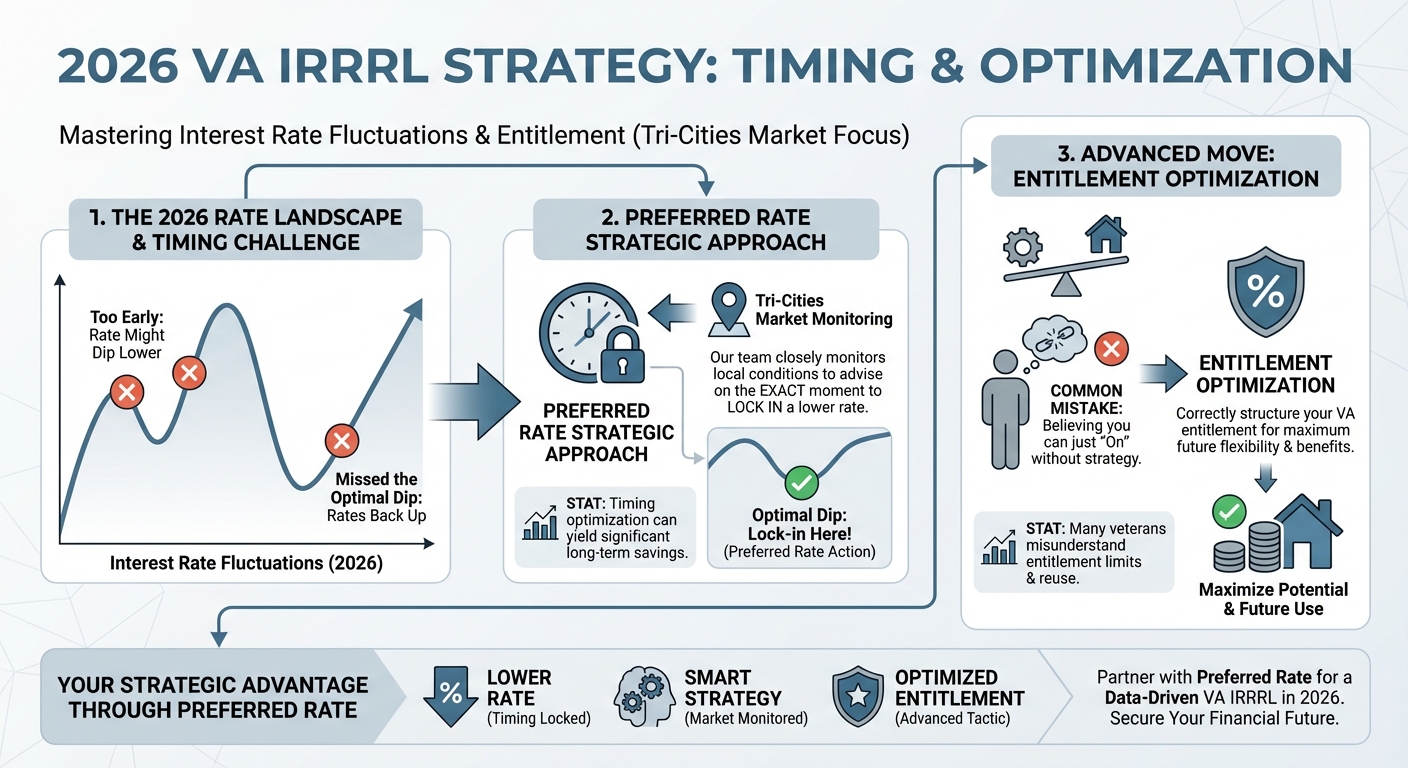
The VA Interest Rate Reduction Refinance Loan (IRRRL) is one of the most powerful tools available to veterans, but timing is everything. In 2026, interest rate fluctuations require a strategic approach. You do not want to refinance too early or miss the optimal dip. Our team closely monitors the Tri-Cities market to advise you on the exact moment to lock in a lower rate through Preferred Rate.
Another advanced move involves entitlement optimization. Many veterans mistakenly believe they can only use their VA loan benefit once. In reality, you can have multiple VA loans at the same time if you have remaining bonus entitlement. Here is how you can maximize this benefit:
- Keep your current home as a rental property and use your remaining entitlement to buy a new primary residence in Southwest Virginia.
- Calculate your available entitlement based on the current conforming loan limits for Washington County or Sullivan County.
- Consult with a mortgage expert to ensure your debt-to-income ratio aligns with VA guidelines.
By leveraging these strategies, you can build a robust real estate portfolio while enjoying zero down payment requirements and no private mortgage insurance.
| VA Loan Feature | Standard Industry Practice | The Arrowood Team 2026 Strategy |
|---|---|---|
| Minimum Credit Score | 620 to 640 | Flexible options down to 580 |
| IRRRL Timing | Reactive to customer requests | Proactive market monitoring |
| Entitlement Use | One-time use assumption | Multi-property optimization |
| Local Program Pairing | Standard VA funding only | Paired with TN & VA grants |
Pairing VA Loans with Tri-Cities Local Incentives
One of the most lucrative, yet underutilized, strategies in 2026 is pairing your VA loan with local homebuyer incentives. Southwest Virginia and the Tennessee Tri-Cities offer various programs that can cover closing costs or provide additional financial support. Because VA loans already require zero down payment, applying these local grants can mean moving into your new Johnson City home with virtually zero out-of-pocket expenses.
Working with a knowledgeable local broker is crucial. Tim Arrowood and his team have deep roots in the community and understand the nuances of both Tennessee Housing Development Agency (THDA) programs and Virginia Housing grants. We seamlessly integrate these local benefits with your VA loan to ensure you get the absolute best deal possible. Are you ready to explore your options? Visit The Arrowood Team website to start your journey today.
Q1: What is the minimum credit score for a VA loan in Johnson City?
While many lenders require a score of 620 or higher, The Arrowood Team offers flexible VA loan options with credit scores down to 580.
Q2: Can I use my VA loan benefit more than once?
Yes, you can use your VA loan benefit multiple times. You can even have two VA loans simultaneously if you have enough remaining bonus entitlement.
Q3: When is the best time to use a VA IRRRL in 2026?
The best time to use an Interest Rate Reduction Refinance Loan is when current market rates are significantly lower than your existing rate and you have made at least six consecutive on-time payments on your current VA loan.
Q4: Do VA loans require private mortgage insurance?
No, one of the biggest advantages of a VA loan is that it does not require private mortgage insurance (PMI), which can save you hundreds of dollars each month.
Q5: Can I pair a VA loan with local Tennessee or Virginia housing grants?
Absolutely. We specialize in pairing VA loans with local incentives in the Tri-Cities and Southwest Virginia to help cover closing costs and reduce your out-of-pocket expenses.
Contact Tim Arrowood Today to Maximize Your VA Loan Benefits
Related guides from The Arrowood Team
- VA Home Loans in Johnson City & the Tri-Cities
- VA Home Loans in the Tri-Cities 2026: Residual Income, Occupancy, and What Mountain Home and ETSU Veterans Should Check First
- VA One-Time-Close Construction in the Tri-Cities 2026: What Veterans Should Ask Before the Slab
- VA One-Time Close Construction Loans: Building Your Home in Johnson City, TN
Ready to move forward? Start your application or see how the $5,000 Closing Guarantee strengthens your offer.
