
Your 2026 Homeownership Roadmap: Smart Strategies for Buying, Refinancing, and Building Wealth in Johnson City

The landscape of real estate is constantly shifting. As we look ahead, savvy homebuyers and homeowners in Johnson City, TN, and the surrounding Tri-Cities area are asking the same question: “How do I position myself for success in the coming year?” Whether you are looking to purchase your first home, upgrade to a forever home, or leverage equity through refinancing, having a clear plan is non-negotiable.
At The Arrowood Team at Preferred Rate, we believe that buying a house shouldn’t be stressful—it should be a strategic step toward financial freedom. Led by Tim Arrowood, our team is dedicated to helping you navigate the complexities of the mortgage market with confidence. This is your comprehensive roadmap to homeownership and wealth building for 2026.
1. Assessing the Terrain: The Johnson City Real Estate Market
Before diving into loan products, it is crucial to understand where we are locally. Johnson City continues to be a desirable hub in East Tennessee, offering a blend of Appalachian charm and economic growth. However, market dynamics are changing.
For 2026, we anticipate a continued focus on affordability and inventory. Buyers who are prepared with pre-approvals and a solid understanding of their budget will have the upper hand. Unlike the frenzy of previous years, the 2026 market demands a more calculated approach—one where your mortgage strategy is just as important as the property you choose.
2. Strategic Buying: Matching Your Goals to the Right Loan
One size does not fit all in mortgage lending. To build wealth effectively, you need a loan structure that aligns with your long-term financial picture. Here is how The Arrowood Team helps you choose the right vehicle for your journey:
The Power of Conventional Loans
For buyers with strong credit (typically 620+) and a stable down payment, Conventional loans remain the gold standard. In 2026, we are seeing competitive terms for conventional borrowers. These loans often have lower mortgage insurance costs (which can be removed once you reach 20% equity) and offer flexibility for primary residences, second homes, and investment properties.
FHA Loans: The First-Time Buyer’s Best Friend
If you are buying your first home in Johnson City, an FHA loan might be your strategic entry point. Backed by the Federal Housing Administration, these loans allow for down payments as low as 3.5% and are more forgiving regarding credit scores. In a market where cash preservation is key, an FHA loan allows you to get into a home sooner and start building equity rather than waiting years to save a larger down payment.
VA Loans: Honoring Those Who Serve
We are proud to serve veterans in the Tri-Cities area. If you are eligible, a VA loan is arguably the best wealth-building tool available. With $0 down payment requirements and no monthly mortgage insurance, VA loans allow veterans to keep their liquidity while acquiring real estate assets. If you have served, ask Tim Arrowood about how to maximize your Certificate of Eligibility (COE) in 2026.
USDA Loans: Capitalizing on Rural Development
Many areas surrounding Johnson City fall under “rural” designations by the USDA. A USDA Rural Development loan offers 100% financing (zero down payment) for eligible properties and borrowers. This is a fantastic option for those looking to buy in the quieter outskirts of Washington, Carter, or Unicoi counties while keeping their savings intact.
3. The “Closing Guarantee”: Our Commitment to You
In a competitive market, a generic pre-approval letter isn’t enough. Sellers want certainty. This is where The Arrowood Team’s Closing Guarantee sets you apart. We don’t just hope your loan closes; we structure our process to ensure it does.
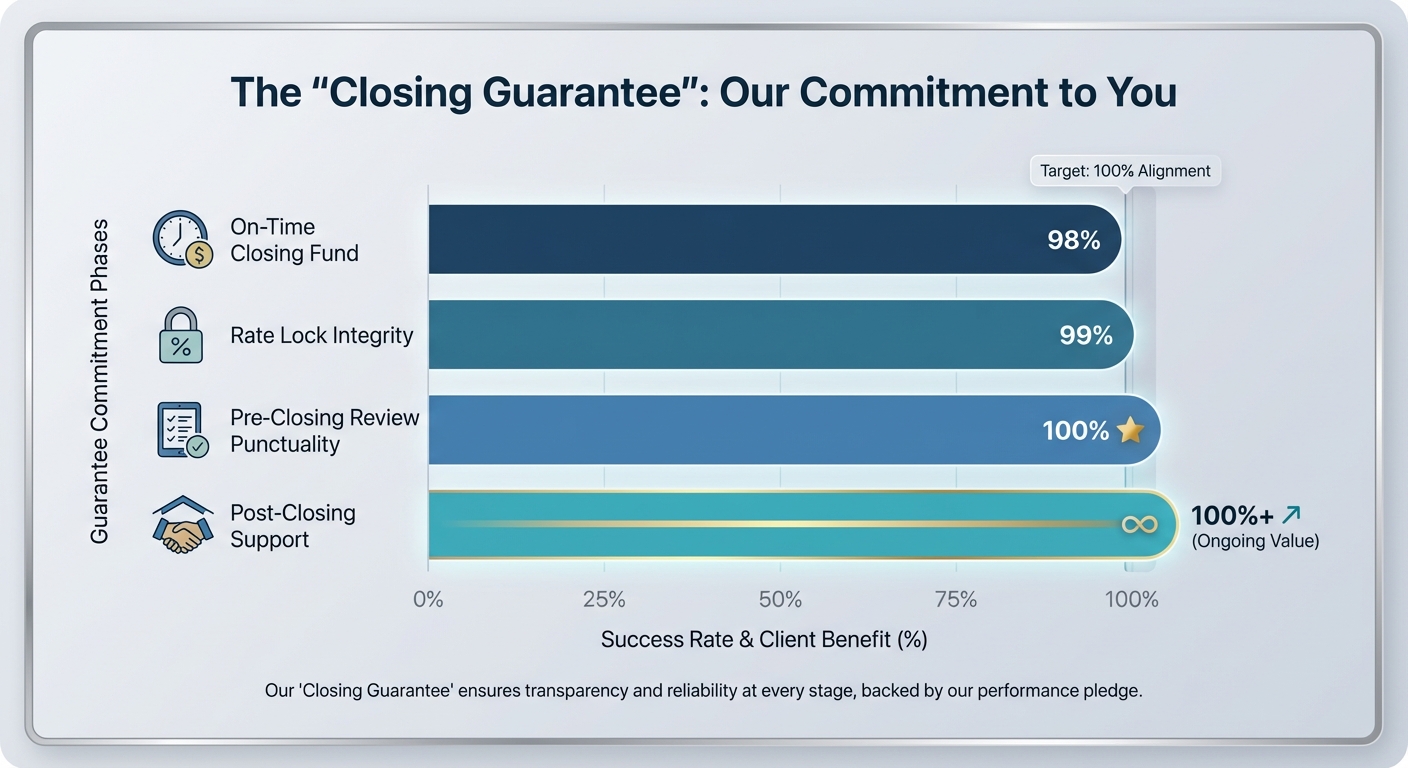
Our “Finding a Way” philosophy means we dig deep into your financial profile upfront. By doing the heavy lifting early, we can present offers that sellers trust. In 2026, a reputation for reliability will be your strongest negotiation currency.
4. Refinancing Strategies for 2026
Homeownership is not a static event; it is an active investment. Refinancing isn’t just about dropping your interest rate—it’s about cash flow management.
- Rate-and-Term Refinance: If rates dip in 2026, refinancing can lower your monthly payment, freeing up cash for other investments or savings.
- Cash-Out Refinance: Johnson City home values have seen appreciation. A cash-out refinance allows you to tap into that equity to fund home renovations (increasing value further), pay off high-interest debt, or even fund a down payment on an investment property.
- Debt Consolidation: With consumer debt rising, using your mortgage to consolidate high-interest credit cards into one tax-deductible*, lower-interest payment can be a smart wealth-preservation move.
5. Comparison: Which Path Fits Your 2026 Goals?
Loan Type Ideal Borrower Profile Primary 2026 Benefit Conventional Strong credit, 3-20% down payment available. Flexibility and elimination of mortgage insurance over time. FHA First-time buyers, lower credit scores, low down payment. Easier qualification to enter the market now rather than later. VA Veterans and active military. $0 Down, No PMI. Maximum wealth retention. USDA Buyers in rural eligible areas with income limits. 100% Financing allows entry with minimal cash to close.
6. Building Wealth Through Real Estate Investment
The ultimate goal of the 2026 roadmap is not just housing—it is wealth. Real estate remains one of the most reliable hedges against inflation. By working with Preferred Rate, you can explore options for purchasing multi-unit properties or investment homes in Johnson City.
Consider “house hacking”—buying a duplex with an FHA loan, living in one side, and renting out the other. This strategy can significantly offset your mortgage payment and accelerate your path to financial independence.
Frequently Asked Questions (FAQs)
1. Is 2026 a good time to buy a home in Johnson City, TN?
2. How much down payment do I really need?
Many buyers believe they need 20% down, but that is a myth. With FHA loans (3.5%), Conventional loans (as low as 3%), and VA/USDA loans (0%), you can enter the market with significantly less capital. We can help you determine the most strategic down payment amount for your specific situation.
3. What is the Arrowood Team’s “Closing Guarantee”?
Our Closing Guarantee is our promise of reliability. It means we have vetted your file thoroughly. If we issue a full approval and the loan fails to close due to an error on our part, we stand by our commitment. This gives sellers peace of mind when accepting your offer. (Contact us for specific terms and conditions).
4. Can I buy a home if I have student loans?
Absolutely. Loan programs have evolved in how they calculate student loan debt relative to your income. Even if you have significant student debt, there are strategies—particularly with FHA and Conventional loans—that can help you qualify. Don’t disqualify yourself before talking to a professional.
5. How do I start the pre-approval process with Tim Arrowood?
Starting is simple. You can reach out to us directly via phone or apply online. We will review your credit, income, and assets to provide a clear budget. From there, we work with your real estate agent to find the perfect home.
Start Your Journey Today
2026 is approaching fast. Whether you are looking to plant roots in Johnson City or optimize your current mortgage, you need a partner who understands the local market and the lending landscape. At The Arrowood Team, we don’t just close loans; we open doors to financial futures.
Ready to map out your homeownership goals?
Contact Tim Arrowood and The Arrowood Team at Preferred Rate today.
Call us at (423) 200-4984 or visit arrowoodteam.com to get started.
The Arrowood Team | Preferred Rate – Partnered with APM. NMLS #1956. Tim Arrowood Originating Branch Manager | NMLS#393468. Equal Housing Lender. All loans subject to credit approval. Rates and fees subject to change. This is not a commitment to lend. Johnson City, TN.
Related guides from The Arrowood Team
- First-Time Home Buyer Loans in Johnson City, TN
- Your Guide to a First-Time Homebuyer Mortgage in Johnson City
- First-Time Homebuyer’s Roadmap for 2026: Overcoming Affordability in Johnson City, TN
- THDA and Tri-Cities First-Time Buyers 2026: Down Payment Help for Johnson City, Kingsport, and Bristol
Ready to move forward? Start your application or see how the $5,000 Closing Guarantee strengthens your offer.
